By Joseph Wong
For many Malaysians, owning a home represents the ultimate financial milestone. It is a physical anchor for personal security, wealth creation and generational stability. Yet, as the national economy evolves and workplace dynamics shift toward non-traditional employment, the traditional mortgage underwriting process has increasingly become a major obstacle for aspiring buyers.
With gig-economy workers, freelancers, micro-entrepreneurs and young professionals making up a growing share of the workforce, the rigid requirement for standardised documentation such as three-to-six months of fixed payslips, long-term employment contracts and flawless traditional credit histories no longer reflects economic realities.
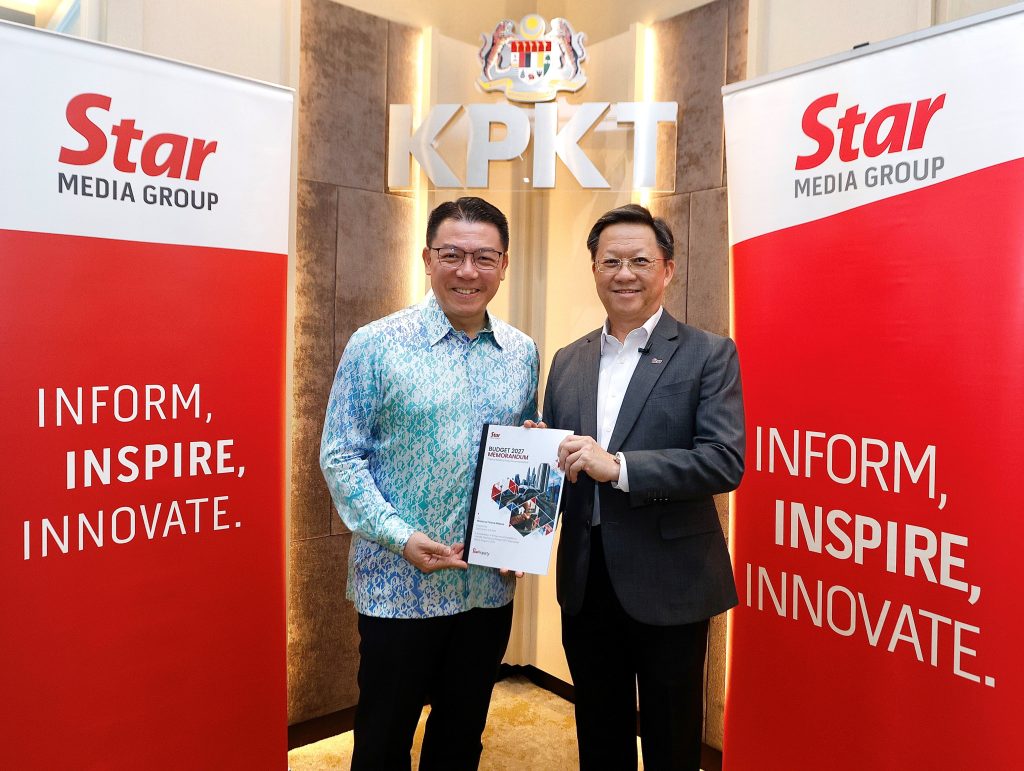
To address this structural mismatch, the Real Estate and Housing Developers’ Association (Rehda) and industry leaders at the StarProperty Budget 2027 Roundtable are calling for a comprehensive expansion of flexible end-financing mechanisms. By broadening the scope of government-backed guarantees like the Housing Credit Guarantee Scheme (SJKP), enhancing step-up financing models and introducing targeted deposit assistance, policymakers can bridge the gap between creditworthy buyers and homeownership.
Why traditional credit frameworks fail modern buyers
The demand for affordable housing remains strong across Malaysia but the primary bottleneck has shifted from supply availability to end-financing approval. Under standard commercial banking criteria, loan applicants without traditional corporate documentation are frequently categorised as high-risk, regardless of their actual net earnings or debt-servicing ability.
Highlighting this friction point, Rehda president Datuk Zaini Yusoff noted that eligibility screening for state-level affordable housing programs reveals alarmingly high rejection rates due to strict banking requirements.
"Our wishlist is for the government to expand the allocation for SJKP, so that more people can be covered," Zaini said. "We do notice that, say, the LPHS (Selangor Housing and Property Board) has an 80% to 90% rejection rate for applicants which means this group of people have difficulty in accessing financing and coming up with down payments."
When four out of five applicants screened for affordable housing are turned away by financial institutions, it signals a systemic disconnect. Freelancers, ride-hailing drivers, e-commerce vendors and gig professionals often generate sufficient aggregate income to service monthly instalments, yet lack the rigid paperwork required by conventional credit risk algorithms.
Protecting lenders while expanding access
Established to assist home buyers without fixed income documentation, the SJKP serves as a vital credit-enhancement tool. By offering a government-backed guarantee on housing loans up to RM500,000, the scheme absorbs a portion of the credit risk, enabling commercial banks to approve financing for non-traditional borrowers.
However, industry leaders emphasise that current allocation levels and fee structures limit the scheme's overall reach. During the StarProperty Budget 2027 Roundtable, Sabah Housing and Real Estate Developers Association (Shareda) deputy president Benny Ng advocated for broader SJKP funding and clearer interest rate structures:
"The government right now is putting up a lot of budget in SJKP, the credit guarantee scheme. I think it helps a lot but it has to go up. The biggest issue with SJKP is that lending banks impose a percentage spread due to higher credit risk. The government should take up this cost rather than passing another 1% to 2% burden onto the buyer."
By absorbing guarantee fees and expanding total SJKP allocations in Budget 2027, the government can encourage participating financial institutions to underwrite loans for self-employed applicants without adding extra interest rate penalties.
Down payment remains the main hurdle
Even when young professionals possess stable incomes, the requirement for an upfront 10% cash down payment, combined with legal fees, stamp duties and valuation charges, often forms an insurmountable entry barrier. A young buyer earning a respectable salary may easily afford a monthly mortgage payment of RM1,800, yet struggle to accumulate RM50,000 to RM60,000 in liquid cash reserves.
Reflecting on the challenges faced by younger buyers, Glomac Bhd group executive director FD Idzham pointed out that upfront capital is often a bigger obstacle than monthly instalment capability:
"The issue I come across is always the differential sum for these young buyers. They don't mind making the monthly payment—the monthly payment is not the main issue. It's always the RM50,000 to RM60,000 deposit you have to put down first for a RM500,000 home. If we can get targeted incentive structures or tiered step-up loan payments through bank platforms where buyers start with lower initial instalments and step up 5 years later, that directly addresses the barrier," he said.
Step-up loan products such as those introduced by select progressive banks allow young buyers to enter the property market earlier in their career trajectory, matching lower initial payments with projected income growth over time.
Educating the next-gen buyers
Beyond structural banking reforms, industry stakeholders stress that expanding flexible financing must be paired with early financial education.
Speaking at the roundtable, UEM Sunrise Bhd chief financial officer Hafizuddin Sulaiman underscored the need to guide younger generations on credit health and long-term asset accumulation:
"There is a lot more education that needs to be done for the younger generation because many don't typically prioritise homeownership as a high priority in their life goals. Many struggle with their credit scores early on because they prioritise car ownership or lifestyle expenses first. As an industry, we have to do better at educating younger generations on the importance of building credit health and participating in real estate as an investment asset class."
As Malaysia moves toward Budget 2027, expanding flexible end-financing is essential for maintaining a healthy housing market. Bridging the gap between creditworthy buyers and homeownership requires modernising underwriting standards to reflect today's workforce.
By expanding the SJKP, encouraging step-up loan structures, absorbing risk guarantee premiums and promoting financial literacy, policymakers and financial institutions can create a more accessible property ecosystem, ensuring that every hardworking Malaysian has a fair path to homeownership.
This article was first published in StarBiz 7.
Stay ahead of the crowd and enjoy fresh insights on real estate, property development and lifestyle trends when you subscribe to our newsletter.