Contributed by Foo Chee Hung
At the beginning of 2026, the consensus surrounding the Malaysian property sector was overwhelmingly optimistic. Real estate analysts and market experts widely projected that the year would serve as the official launchpad for a powerful new real estate up-cycle. These glowing early-year forecasts were heavily anchored on robust macroeconomic fundamentals, including a solid 6% national economic growth projection, a stable Overnight Policy Rate (OPR) maintained at 2.75% and proactive government initiatives designed to stimulate housing demand.
However, looking back at these predictions from the vantage point of late 2026, a significant divergence has emerged between early expectations and the actual transactional data. To validate the early-year predictions of a new upward expansion, 2026 performance must, at a minimum, keep pace with or outpace the historic benchmarks established in 2025.
Despite a slight seasonal uptick in Q3 2026 (which recorded 108,990 transactions worth RM60.31bil), cumulative data from the first nine months of 2026 reveals a trailing deficit that makes an annual uptrend mathematically improbable. In terms of property transaction volume, the first nine months of 2026 recorded 296,310 transacted units — accounting for 71.16% of 2025’s full-year total (416,413 units). In terms of property transaction value, cumulative market liquidity reached RM165.43bil, which represents 68.40% of 2025’s full-year value (RM241.87bil) (see Figure 1).
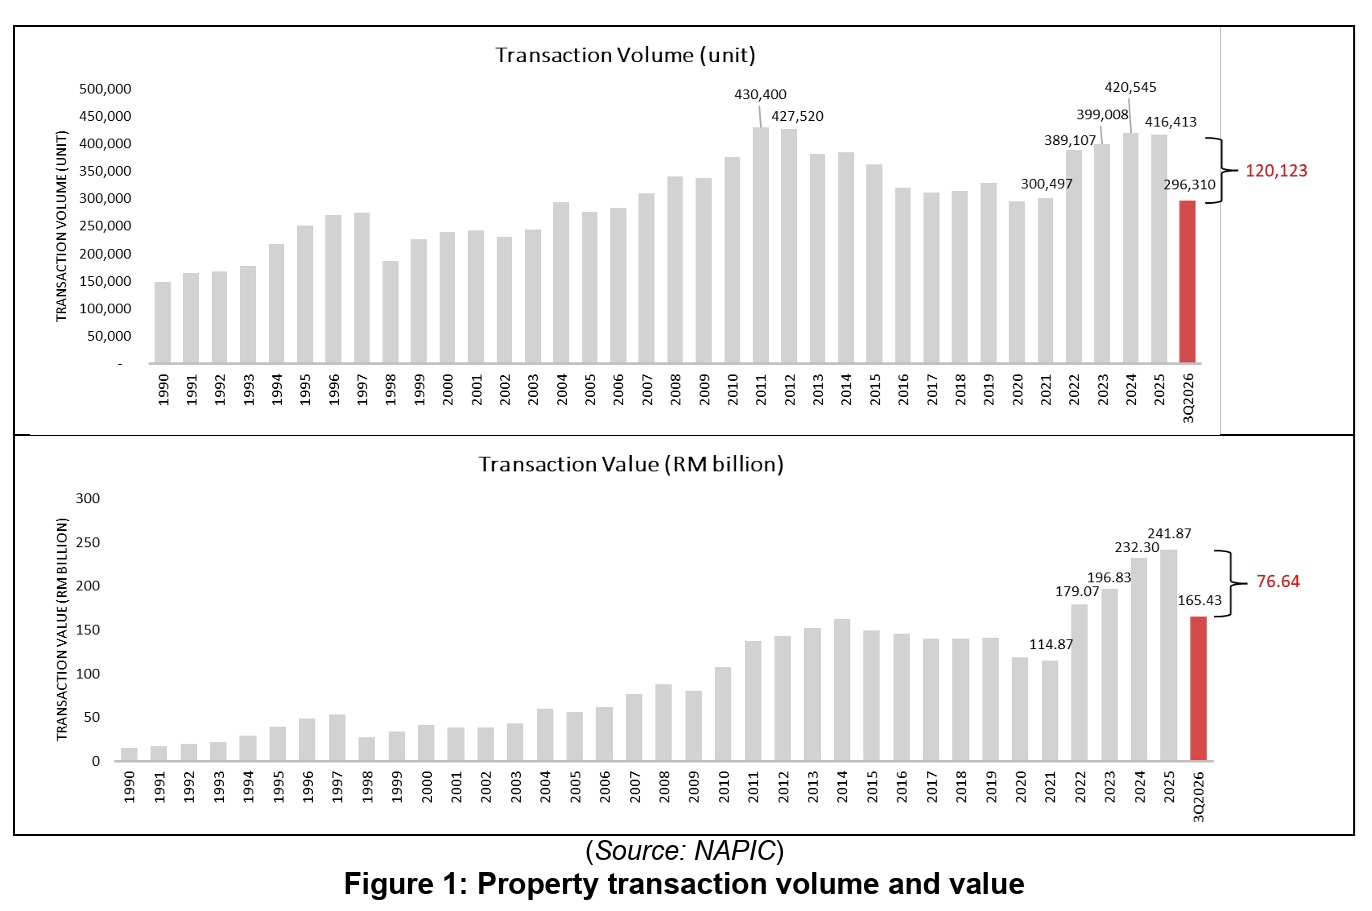
From a neutral perspective, for 2026 to fulfil the up-cycle narrative and at least match 2025's, the final quarter of the year (Q4) must shoulder an immense burden. It would need to secure 120,123 units and RM76.64bil in value — requiring Q4 to outperform Q3's transaction value by nearly 27%. Given that ground-level buying momentum remains constrained by both cautious consumer sentiment and tightening credit conditions, expecting such a drastic, single-quarter surge in transaction velocity is unrealistic.
Primary market absorption has steadily deteriorated across comparable third-quarter windows — sliding from 22.0% in Q3 2024, down to 14.0% in Q3 2025 and halving again to a dismal 7.1% in Q3 2026 (where only 1,387 out of 19,642 newly launched units were absorbed).
Housing loan approval dropped
Compounding this weak buyer appetite, Malaysia’s housing loan approval rate dropped to 38.36% in September 2026 (down from the 40% – 41% baseline recorded between 2022 and 2025), as banks apply stricter scrutiny to borrower creditworthiness, property valuations and project viability. With primary sales stalling and fewer loan applications converting into approved mortgages, the actual runrate points toward an annual consolidation or mild contraction rather than an upward expansion.
The primary defence for an up-cycle prediction usually relies on asset price appreciation. Yet, looking at the Q3 2026 results, the Malaysian House Price Index (IHRM) registered an annual growth rate of just 0.5%, decelerating further from the 0.9% recorded at mid-year. High-rise properties even recorded a negative annual price adjustment of -0.7%.
In macroeconomic analysis, asset price growth below 1% indicates a market that has largely flatlined, failing to keep pace with broader inflationary pressures. A genuine, aggressive new growth cycle typically exhibits robust, compounding price index expansions. A near-zero growth rate implies that market momentum is actively cooling, directly contradicting the early-year theories of an accelerating trend. The most compelling evidence that early-year outlooks may have been misleading lies in the escalating volume of unsold inventory.
As of 3Q 2026, the total property overhang has climbed further to 57,166 units, consisting of 33,598 residential housing units (worth RM19.55bil) and 23,568 serviced apartments (worth RM20.13bil) (see Figure 2).
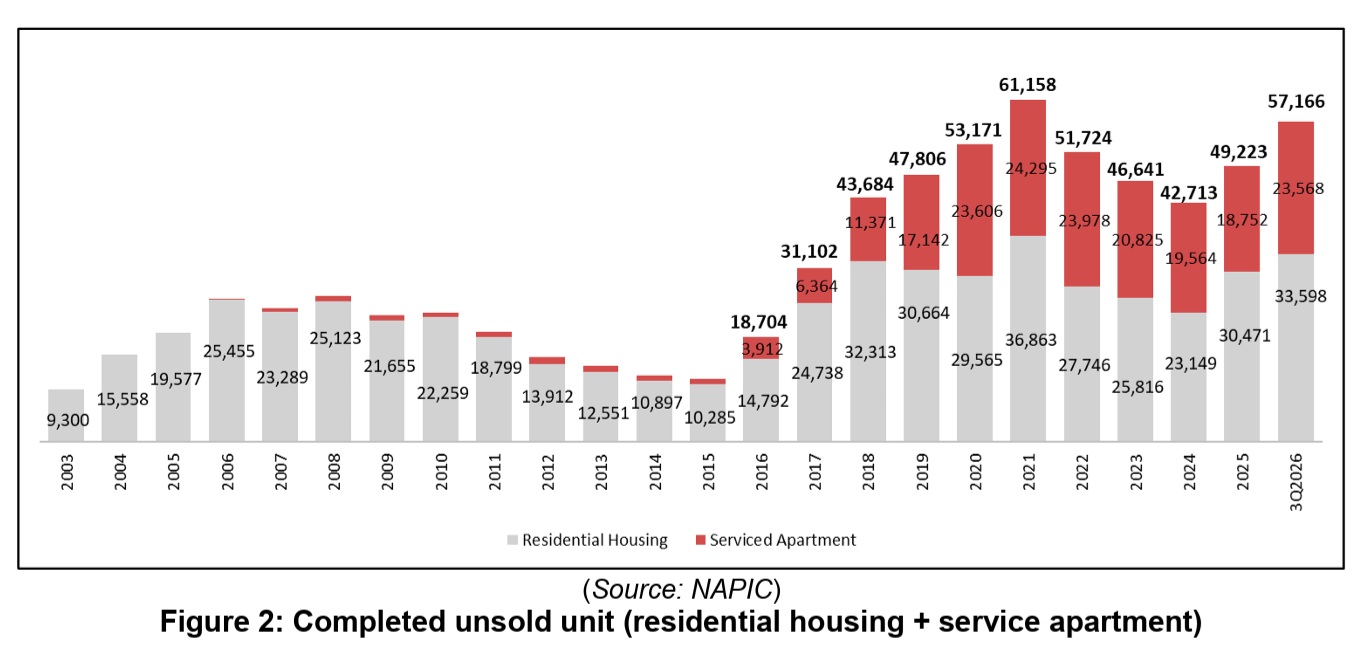
To understand why the new cycle predictions missed the mark, one can benchmark these third-quarter figures against the 2018 – 2019 period — the exact historical window when the Malaysian property market famously entered its last major structural slowdown.
The years 2018 and 2019 were the exact tipping point where demand fatigue set in and the last property boom froze. The fact that the 3Q 2026 residential overhang has risen even higher above that historical threshold while unsold serviced apartments have more than doubled (+107.3%) since 2018 proves that the market is still grappling with a structural oversupply issue, rather than riding a new wave of expansion.
This structural imbalance is equally visible across the non-residential sector, where commercial space absorption continues to trail new supply completions. In the retail segment, overall occupancy slid to 76.6% in Q3 2026, down from 77.9% in Q2 2026 and 78.6% a year earlier.
Notably, total occupied space actually contracted slightly from about 146.5 million sq ft in Q2 to approximately 145.96 million sq ft in Q3, even as total retail space expanded to an estimated 82.88 million sq ft. Traditional shopping malls faced even sharper headwinds, with occupancy rates dropping to 74.1% in Q3 2026 compared to 76.8% in Q3 2025, reflecting persistent tenant consolidation and cautious retail spending.
Warning signs
Meanwhile, purpose-built offices saw only marginal stability, with overall occupancy edging up slightly to 78.8% (and private-sector offices reaching 73.0%). However, with over 21% of total office space, and more than a quarter of retail mall space, remaining vacant nationwide, the commercial landscape reinforces the broader narrative of a market still digesting excess capacity.
When an independent observer cross-examines the early-year new up-cycle forecasts against the empirical evidence of trailing the first nine months of transaction deficits, weak primary launch sales and an expanding overhang, the optimistic near-term predictions lose their analytical footing. The Q3 data clearly demonstrates that the property market is not entering a period of immediate transactional acceleration.
Instead, it is closely mirroring the warning signs of the 2018 structural freeze: flatlining price growth, a widening transactional deficit and a heavy inventory glut. In retrospect, labelling 2026 as the immediate launchpad for a transactional property uptrend has proven to be a miscalculation. However, this does not mean the long-term outlook for the country is entirely bleak.
The bullish predictions made by market experts may only hold weight if we redefine the term uptrend. Rather than expecting an immediate surge in consumer transaction volumes today, any future growth cycle must be viewed as a slow, long-term structural reset for 2027 and beyond — one that will be driven strictly by macroeconomic shifts like industrialisation, foreign direct investment and major infrastructure rollouts.
For the current calendar year, the hard data simply does not support a consumer-led boom. A realistic, data-grounded assessment firmly positions 2026 as a year of necessary structural consolidation and cautious market navigation. Stakeholders and investors who look past the early-year hype and respect the third-quarter reality will be far better equipped to manage risks until a genuine, fundamentally sound cycle begins to take shape.

This article was first published in StarBiz 7.
Stay ahead of the crowd and enjoy fresh insights on real estate, property development, and lifestyle trends when you subscribe to our newsletter and follow us on social media.